The global HDI PCB market is projected to hit $21.26 billion in 2026, growing at a CAGR of 8.5% as AI server deployments, high-performance computing infrastructure, and substrate-like PCB (SLP) technology reshape the printed circuit board industry. For electronics manufacturers and OEMs, the message is clear: HDI capability is no longer optional — it's the price of admission.
AI Servers: The Engine Behind HDI Demand
The AI server HDI PCB segment alone was valued at $14.02 billion in 2025 and is projected to grow at a staggering 14.89% CAGR through 2026, according to industry analysis. NVIDIA's GB200, AMD's MI400 series, and custom ASICs from hyperscalers are all driving unprecedented demand for high-layer-count, low-loss HDI boards capable of handling 800G and 1.6T interconnects.
"Traditional FR-4 multilayer designs have hit their physical limits," notes a recent NextPCB analysis. "HDI PCBs — with microvias, finer traces below 50μm, and advanced stackups — are the only viable path for AI hardware that demands signal integrity at extreme speeds."
SCHMID Group's Major Order Signals Capacity Expansion
In March 2026, SCHMID Group (NASDAQ: SHMD) secured a lower two-digit million-USD purchase order for multiple wet-process systems to equip a new HDI multilayer production line. The order underscores how PCB fabricators worldwide are aggressively expanding HDI capacity to meet surging AI infrastructure demand.
The equipment will support production of HDI boards with layer counts exceeding 24 layers, fine-line etching below 30μm, and via filling processes essential for AI server backplanes and accelerator cards.
Substrate-Like PCB (SLP): Bridging the Gap
The substrate-like PCB market is emerging as the critical bridge between traditional PCB and semiconductor substrate manufacturing. With modified semi-additive process (mSAP) technology enabling line/space widths of 20/20μm and below, SLP is being adopted for mobile devices, AI edge computing modules, and advanced packaging substrates.
Key market drivers include:
- Miniaturization pressure — AI wearables and edge devices demand smaller form factors
- Signal integrity — 5G/6G and high-speed serial links require tighter impedance control
- Thermal management — AI chips generate 300W+ requiring advanced PCB thermal solutions
- Supply chain diversification — OEMs seek HDI/SLP capacity outside traditional East Asian hubs
What This Means for PCBA Partners
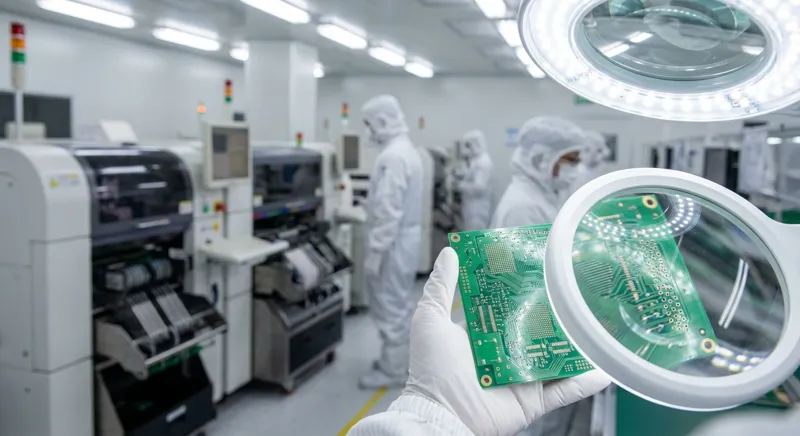
For contract manufacturers and EMS providers, the HDI surge creates both opportunity and challenge. Building HDI capability requires significant capital investment — laser drilling equipment, mSAP lines, and advanced AOI systems can run into tens of millions of dollars per production line.
Key considerations for OEMs selecting a PCBA partner in 2026:
- Microvia capability — Can the partner reliably produce stacked and staggered microvias at volume?
- DFM expertise — Does the partner offer design-for-manufacturing review specific to HDI?
- Material supply — Access to high-Tg, low-Dk/Df materials (Megtron 6, IS410, etc.)
- Turnkey integration — BOM management, component sourcing for 01005 and below, and SMT placement accuracy
- Testing infrastructure — Flying probe, ICT, and functional test for complex HDI assemblies
Illuminious: HDI-Ready Manufacturing at Scale
Illuminious LLC has positioned its global manufacturing network to support the HDI PCB demand surge. With facilities in Southeast Asia — including Batam's Free Trade Zone and Vietnam operations — Illuminious offers HDI PCBA services with competitive turnkey solutions for AI, HPC, and telecommunications applications.
"The AI infrastructure buildout isn't slowing down — it's accelerating," said an Illuminious spokesperson. "Our investment in HDI capability, from laser drilling to mSAP-adjacent processes, ensures our clients can scale from prototype to volume production without switching manufacturing partners."
The company's turnkey approach — combining PCB fabrication, component sourcing, SMT assembly, and testing under one roof — addresses the integration challenges that HDI designs uniquely present. For OEMs racing to deploy AI hardware, that integration can shave weeks off time-to-market.
Looking Ahead: 2027 and Beyond
Industry forecasts project the global HDI PCB market will reach $34-37 billion by 2032-2033. The AI server PCB segment alone is expected to maintain double-digit growth through the decade, driven by next-gen GPU clusters, inference infrastructure, and edge AI deployments.
For manufacturers and OEMs, the strategic imperative is clear: partner with PCBA providers who have both the technical capability and the capacity to handle the HDI demands of AI-era hardware. The window for building those partnerships is now.